You get the quote, build your budget around it and then the job scope changes after work begins. That can happen on both roofing and siding projects, especially once old materials are removed and concealed conditions become visible.
It helps to separate two documents that homeowners often lump together: the insurance estimate and the contractor’s repair estimate. While they may not be the same amount, both are based on the information available at the time. A later change in cost doesn’t automatically mean a contractor estimated poorly or an insurer acted improperly. The important question is what changed, why it changed and whether the added work is necessary and covered under the policy.
What an Estimate Can Actually See — and What It Can’t
A roofing or siding estimate prices what’s visible on the day someone looks at it. The problem is that the roof and siding can conceal damage to other parts of your home: the decking and sheathing underneath, the wall framing, the house wrap and the flashing at edges and joints.
Until the old surface comes off, no one can say with certainty what shape those hidden layers are in. A drone photo or a walk-around can flag obvious problems, but it can’t see the moisture-damaged sheathing under a slow, years-old leak, the deteriorated decking around a chimney, or the compromised framing behind a section of siding where water has been getting in. Regular inspections and proper maintenance can help catch problems before they reach this point, especially when caring for an aging roof. Even with a careful inspection, some conditions only reveal themselves at tear-off, and they can be a major reason the final cost outruns the estimate.
Siding is no different. Peel back an old panel, and you may find damaged wrap, rusted fasteners or wall sheathing that has to be replaced before new siding can go on correctly.
The Line Items That May Be Left Off
Hidden damage is part of the story. The other part is scope: the specific items a complete, code-correct repair requires that don’t always make it onto the first estimate.
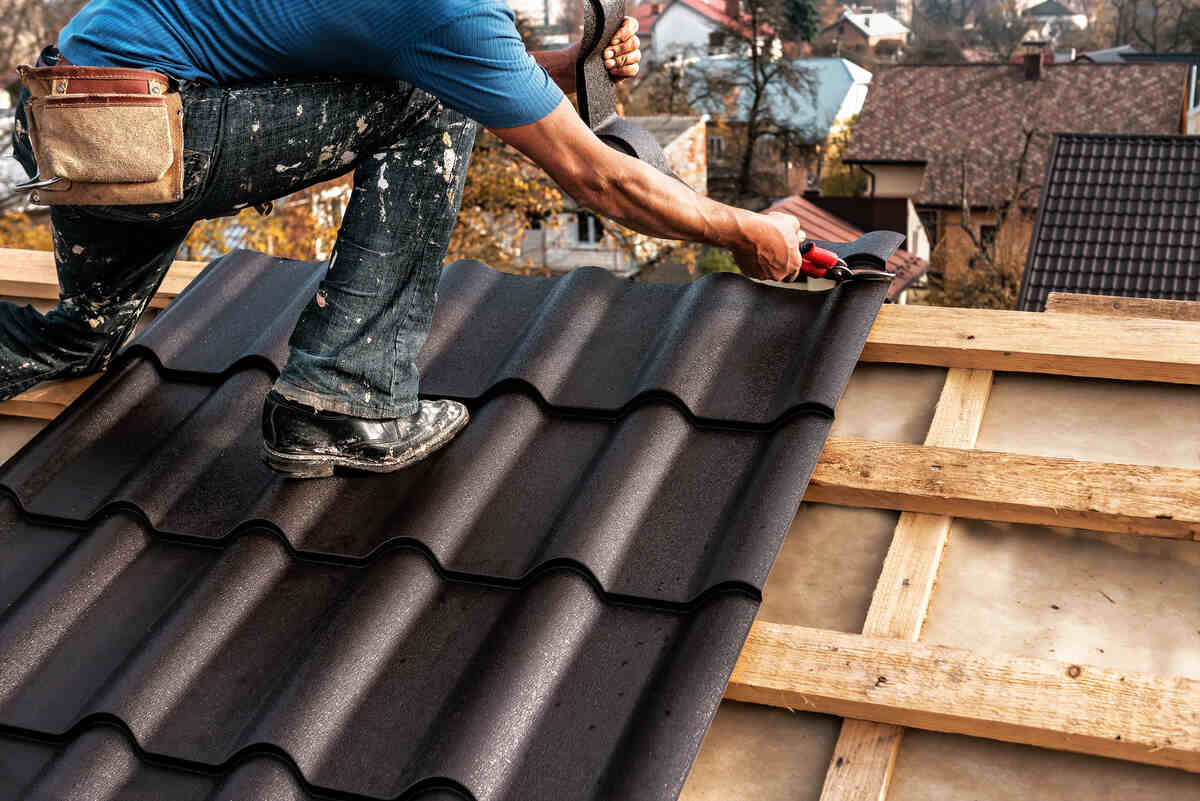
On a roof, the items that may be omitted or require adjustment are familiar to anyone who does this daily: ice-and-water shield where local code requires it, drip edge, proper deck fastening where required, ridge and starter, step and counter-flashing where the roof meets walls and chimneys, and attic ventilation needed to meet applicable code or manufacturer requirements. Add detach-and-reset for anything mounted to the roof, disposal, permits and steep- or high-roof access where applicable, and the difference between an initial estimate and the final scope can add up fast.
None of these are unusual. They’re standard parts of doing the job right; they just don’t always show up on a first pass, especially when the estimate is being built quickly.
Why Insurance Estimates Can Change
If your project is going through a homeowners’ insurance claim, there’s an extra layer worth understanding. The coverage you choose matters when you eventually need to make a claim, which is why it helps to know what to look for in a homeowners insurance policy.
When a carrier pays for a roof or siding repair, the initial dollar figure comes from an adjuster’s estimate, which may be based partly on photos or aerial imagery. Adjusters are working from the information available at the time. Missed items may be identified later, and code-related costs may need to be added. It isn’t necessarily bad faith; it’s often a matter of the information available when the initial estimate was prepared, just with more paperwork riding on it.
“Most short estimates aren’t anyone acting in bad faith,” says Vladimir Shoshon, founder of Claim Supplement Pro and a HAAG-certified estimator. “They’re built off what you can see from the ground or a drone. Some damage that drives cost, like decking or flashing, may not turn up until the shingles come off. The job is to document those additional items properly so the carrier can review whether they belong on the estimate.”
That gap between the carrier’s number and the actual cost of a covered repair is what a supplement is designed to address.
How to Fix It: Close the Gap Before It Costs You
You can’t make hidden damage disclose itself in advance. But you can help keep it from turning into a budget shock and, when insurance is involved, reduce the chance of paying out of pocket for work the policy may cover.
Don’t budget to the exact estimate – Treat the quote as a starting point, not a ceiling, and hold a cushion for what the surface is hiding.
Ask for a real look, not just a surface pass – A good contractor will check the attic for staining on the underside of the deck, look closely at existing flashing and ventilation, and note anything that suggests trouble underneath before finalizing a number.
Insist the estimate ties to documentation – Every added line item should be supported by relevant documentation, such as photos, measurements, code requirements, invoices or manufacturer instructions. A well-documented estimate is easier to review and support if the scope grows.
When insurance is paying and the number won’t cover a proper repair, that’s what the supplement process is for – A supplement is a documented request to the carrier to add the legitimate items that were missed the first time: hidden damage found at tear-off, code-required upgrades, or omitted scope. It’s often handled by the contractor: your roofer or siding contractor either handles it in-house or brings in a specialist. Firms like Claim Supplement Pro review the carrier’s estimate, document what’s missing and prepare a carrier-ready supplement for review – delivering expert roofing supplement services and siding solutions alike. For you, that can help determine which added costs are covered and reduce avoidable out-of-pocket surprises.
The Bottom Line
A roofing or siding estimate that comes in under the real cost isn’t necessarily a warning sign about your contractor. It can happen when you price a repair on something you can’t fully see until you open it up or when additional scope or code-related items need to be added after the initial estimate.
The homeowners who come through a roof or siding project without a budget shock aren’t just lucky. They’re the ones who understood that the surface could hide something, insisted on documentation and understood that when insurance is involved, a supplement is a tool for asking the carrier to review additional covered costs. Understand that going in, and the gap between the quote and the cost is less likely to be a surprise and becomes something you can manage.